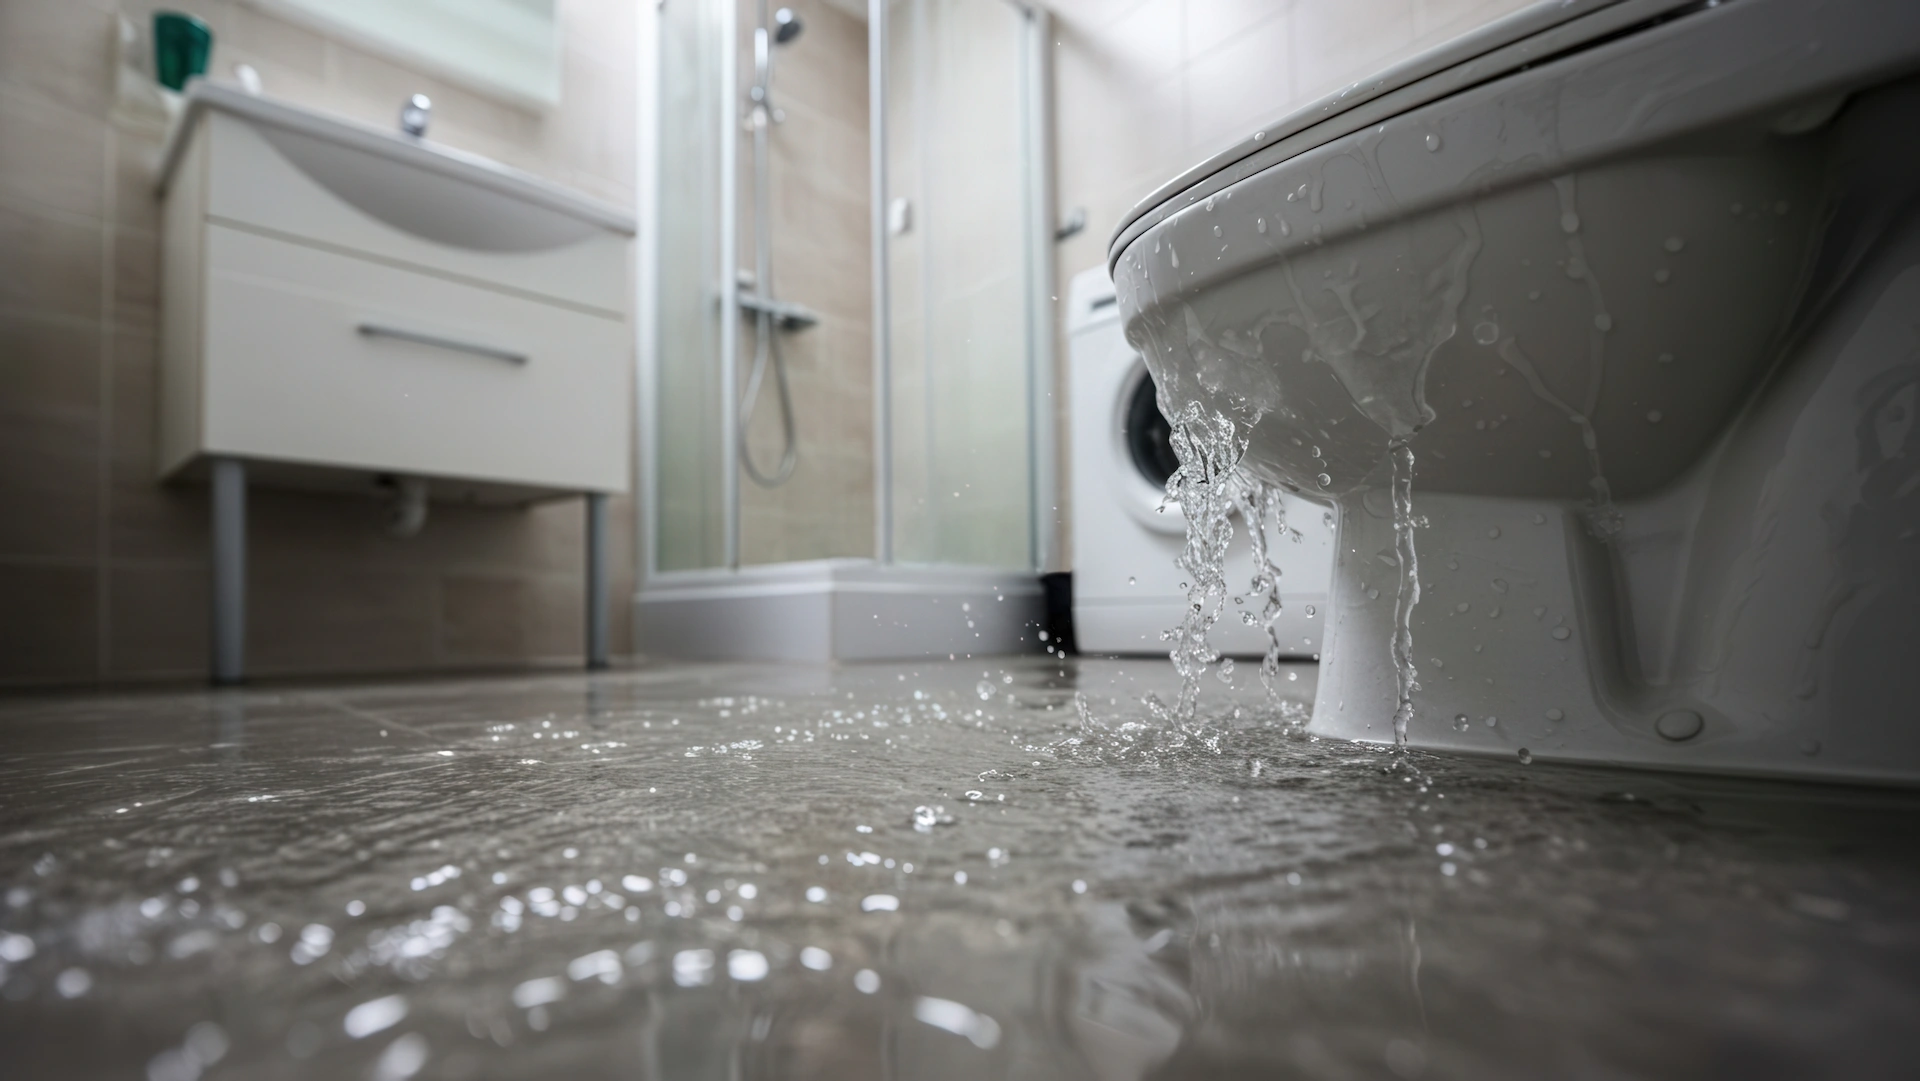
Most Massachusetts homeowners are one bad storm away from a flood they cannot afford. Your homeowners policy does not cover flood damage. Not from a nor’easter. Not from the Merrimack overflowing. Not from three inches of rain in an afternoon. This page explains what flood insurance covers, what it costs in Massachusetts, and how to get a quote in about a minute.
Flood Insurance in Massachusetts: What Homeowners Need to Know
Trusted by Businesses for 30+ years 

Your homeowners policy does not cover floods
This surprises almost everyone. A standard Massachusetts homeowners policy covers fire, wind, theft, and burst pipes. It does not cover damage from rising water, storm surge, or overflowing rivers and streams. That exclusion applies whether you live on Cape Cod or twenty miles inland.
One inch of water in your home can cause $25,000 or more in damage, according to FEMA. Without flood insurance, that bill is yours.
Flooding in Massachusetts is not just a coastal problem
The coast gets the headlines: storm surge on Cape Cod, flooding along the North Shore and South Shore, Boston Harbor at high tide during a nor’easter. But some of the worst flood losses in the state happen inland, along the Merrimack, Charles, and Connecticut rivers, and in low lying neighborhoods where heavy rain overwhelms drainage.
Flood losses happen well outside the mapped high risk zones too. If your lender does not require flood insurance, that does not mean you do not need it.
What flood insurance covers
A flood policy generally covers two things:
Building coverage. The structure itself: foundation, walls, floors, electrical and plumbing systems, furnaces, water heaters, and built in appliances.
Contents coverage. Your belongings: furniture, clothing, electronics, and portable appliances. Note that coverage for belongings kept below ground level, like in a basement, is limited. Ask us what that means for your home.
What it does not cover. Damage from moisture or mold that could have been prevented, currency and precious metals, and living expenses while your home is being repaired. The last one applies under the federal program; private options can differ.
NFIP vs private flood insurance
You have two ways to buy flood insurance in Massachusetts.
The National Flood Insurance Program (NFIP) is the federal program. Coverage is standardized, new policies come with a 30 day waiting period, and the coverage limits have not kept up with Massachusetts home values.
Private flood insurance, like the instant quote product we offer through Neptune Flood, is underwritten by private insurers. It typically offers higher coverage limits, shorter waiting periods, and broader options than the federal program. For many Massachusetts homeowners, private flood costs less and covers more.
From Our Clients

Andrew Senesi
16 hours ago
Geoffrey Cedrone did an excellent job helping me find a new car insurance policy. He answered all my questions and was extremely knowledgeable throughout the entire process. I would absolutely recommend using him, and I will be asking for his help again in the future!

biao huang
3 days ago
Been great working with Sean S for my home insurance. strongly recommend!

Manny Terra
7 days ago
My agent is Paulo Botelho he was great to explain to me about the policy I’ve got and I’m very happy with it and I’m actually referring him to friends and family thank you Paulo

Samuel Silva
7 days ago
We had a wonderful experience working with Paulo Botelho at Segreve & Hall insurance. Paulo has been extremely helpful, knowledgeable, and professional throughout the entire process. He always take the time to answer my questions, explain everything clearly, and make sure we understand our options. His patience, attention to detail, and dedication yo providing excellent customer service are truly appreciated. We highly recommend Paulo to enyone looking for a trustworthy and reliable insurance professional!

anthony carrera
7 days ago
I’ve had a great experience with Segreve & Hall Insurance! Paulo Botelho was great, very professional, and excellent at his work. He was always helpful and quick to answer any questions. I highly recommend their services!

Emily Duseau
1 week ago
I’ve had a great experience with Segreve & Hall insurance and would definitely recommend them! Paulo Botelho is especially helpful and addresses questions right away.

Cristy Donis
1 week ago
Paulo was very helpful and responsive when we needed to get additional insurance for a new contract. Great service from Segreve & Hall.

Larissa Da Silva
1 month ago
I had a great experience Segreve & Hall! They are extremely attentive, professional, and always willing to help. Every time I have a question, they respond quickly and make sure everything is clearly explained. Their customer service is excellent, and I truly appreciate how supportive and reliable they are. It’s great to work with a company that genuinely cares about its clients. Highly recommend!

Phil Murphy
2 months ago
For years my family and I have received outstanding service from Segreve & Hall for our home and auto insurance needs. Their team is knowledgeable, responsive, and always takes the time to explain our options and help us select the right coverage.
Over the past several years due to my experience with them, I have also invested through their financial division, Compass Financial. Their team has provided thoughtful guidance and excellent advice regarding my investments.
I truly appreciate the professionalism, personal attention, and dependable service both companies have provided. I highly recommend Segreve & Hall and Compass Financial to anyone seeking trusted insurance and financial guidance.

Rosella Cedrone
3 months ago
I have been insured with Michael Segreve and continued with Segreve and Hall for over 37 years. My experience with them has always been very informative; positive, pleasant and professional. Michael has guided me financially for many years and without his knowledge of finances I would have never been able to purchase my house and have retirement savings.
The office staff and insurance agents have always been very helpful and supportive no matter what the circumstances are.
I will continue to insure my home, business, all my vehicles and financial needs with Segreve and Hall because they are the best!

Peter Alabiso
4 months ago
I recently rewrote my auto, homeowners and umbrella policies with Segreve and Hall, who came highly receommended. Working with Sean was very straightforward and efficient. All questions were answered, in a very professional manner. A significant savings over the policies my former agent had me in for identical coverage. Very happy with the interaction and result.

Andy Chiango
4 months ago
I have been a client of Segreve and Hall for some time now. I have had nothing but great experiences and interactions with the team at Segreve and Hall. Dan St. Pierre has always been my go to point of contact. Recently, Dan was out and Fin and Michael Brandolini helped me transfer an auto policy. As always the team was great. They quickly worked through the process and got me into a new policy. They have all of my insurance business and I am grateful.

Dreams T.
4 months ago
Michael Brandolini at Segreve Hall was outstanding to work with. He was friendly, professional, and always on top of everything throughout the entire process. He followed up consistently, responded quickly whenever I had questions, and made everything easy and stress-free. On top of providing exceptional customer service, he found me the best price for my car insurance. I truly couldn't have asked for a better agent. I highly recommend Michael to anyone looking for someone who genuinely cares about their clients and goes the extra mile, especially when dealing with car insurances and quotes. I was recommended to reach out to him and he saved me money and time and stress. Thank you Michael; it was much appreciated.

Kellie S
4 months ago
Excellent experience with Segreve & Hall Insurance Associates! Thomas went above and beyond to make sure I had the right coverage and everything was accurate. He also helped resolve an issue with my renters insurance by quickly updating the documentation multiple times, which saved me from unnecessary charges by my apartment complex. The team was always responsive, professional, and genuinely cared about getting everything right. Highly recommend!

Victoria Cusanello
4 months ago
Three generations of my family are insured through Segreve and Hall, and I cannot speak more highly of the service Thomas has provided for us recently. When I needed my car insured after moving back to MA, he took care of everything. It is hard to come by a trustworthy company like Segreve and Hall that consistently exceeds expectations and is so responsive and transparent at the same time. Highly recommend these folks for any and all insurance needs!

Dennis Molla
5 months ago
We've been using S & H Insurance Associates for 10+ years.
I have all of my construction company insurance with them + personal cars and motorcycle.
They work efficiently, get back to me with information quickly, never any problems.
Highly recommend them.

Maryanne Ham
6 months ago
We recently transferred over our insurance and received prompt, kind, and professional support throughout the process. Thomas S made everything easy and took the time to answer our questions clearly. We really appreciated the smooth experience and excellent customer service.

Emad Lababidi
6 months ago
I have been working with S&H insurance for the past few years; I have insured multiple properties and autos. S&H has provided me excellent service, prices and has been responsive to all the questions I had throughout the years. Sean, Dan, Ashley and other staff have been excellent with the attitude and friendliness to work with. They have even asked me to provide my kids school transcript in order to help us reduce the cost of the insurance. They have gone above and beyond in service compared to many insurance companies I have dealt with in the past. They have provided me with many quotes from different sources to compare prices and made the process easy to select the right insurance for us. I would recommend S&H Insurance company to anyone because of the responsiveness, knowledge and reliability.

Tim Klingenberger
7 months ago
Every once in a great while , and seldom these days, you meet a true professional.
Paul Botelho is an absolute Professional.
I was really impressed by Paul and his professional, fast, and friendly service.
He answered all my questions and guided me through the things in needed help on.
After 35 years working with the top luxury brands I can definitely say that Paul provides a high performing top tier service that feels like a luxury experience with great pricing. You’ll be glad you called him. He truly appreciates his clients and it shows.

Etson Tavares
7 months ago
Always great to work with Segreve & Hall. The people there are fantastic, professional and they help make the process simple and stress free. Second time getting a different policy and both times went smoothly. This recent policy was a commercial policy and I was assisted by Paulo. He was extremely helpful and worked diligently to get me the best price possible. Given the current insurance market conditions I’m extremely satisfied with the premium I received. Top notch customer service. More importantly the continued customer support they provide. Highly recommend Segreve and Hall.
What flood insurance costs in Massachusetts
Premiums depend on your flood zone, your home’s elevation, the building type, how much coverage you buy, and your deductible. Homes in high risk zones near the coast pay the most. Homes outside those zones often qualify for surprisingly affordable preferred rates.
The honest way to find out your price is a quote, which takes about a minute with our instant tool.
Do you need flood insurance?
Your mortgage lender requires it if your home sits in a high risk flood zone. But the mandate is not the measure of your risk. About 40 percent of NFIP flood insurance claims come from outside high risk flood zones, according to FEMA. Just because you are not in a mandated flood zone does not mean your property is not at risk. Beyond that, ask yourself three questions. Has your street or neighborhood ever flooded? Is your home near the coast, a river, or low ground? Could you pay for major water damage out of pocket? If you answered yes to any of these, get a quote and compare the annual premium to the risk.
Get an instant flood quote
Our instant flood quote takes about a minute. Enter a few details about the property and see your price right away. There is no obligation, and you can call us at (978) 975-1300 with questions.
Get a instant quote
Frequently asked questions
Does my homeowners insurance cover flooding from a burst pipe?
Yes, that is different. Water damage from a burst pipe inside your home is generally covered by your homeowners policy. Flood insurance covers water that comes from outside: rising water, storm surge, overflowing rivers.
How long before coverage starts?
The federal program has a 30 day waiting period for new policies. Private flood insurance typically starts much sooner. Do not wait until a storm is forecast. By then it is too late.
I am not in a flood zone. Do I still need it?
Flood zones describe lender requirements, not actual risk. Heavy rain, nor’easters, and river flooding damage homes outside the mapped zones every year in Massachusetts.
Can I get flood insurance as a renter?
Yes. Contents only flood policies protect your belongings and they are very affordable.